WEEKLY MARKET OUTLOOK
Constructive, but Awaiting Confirmation
Weekly Market Outlook | September 7, 2026
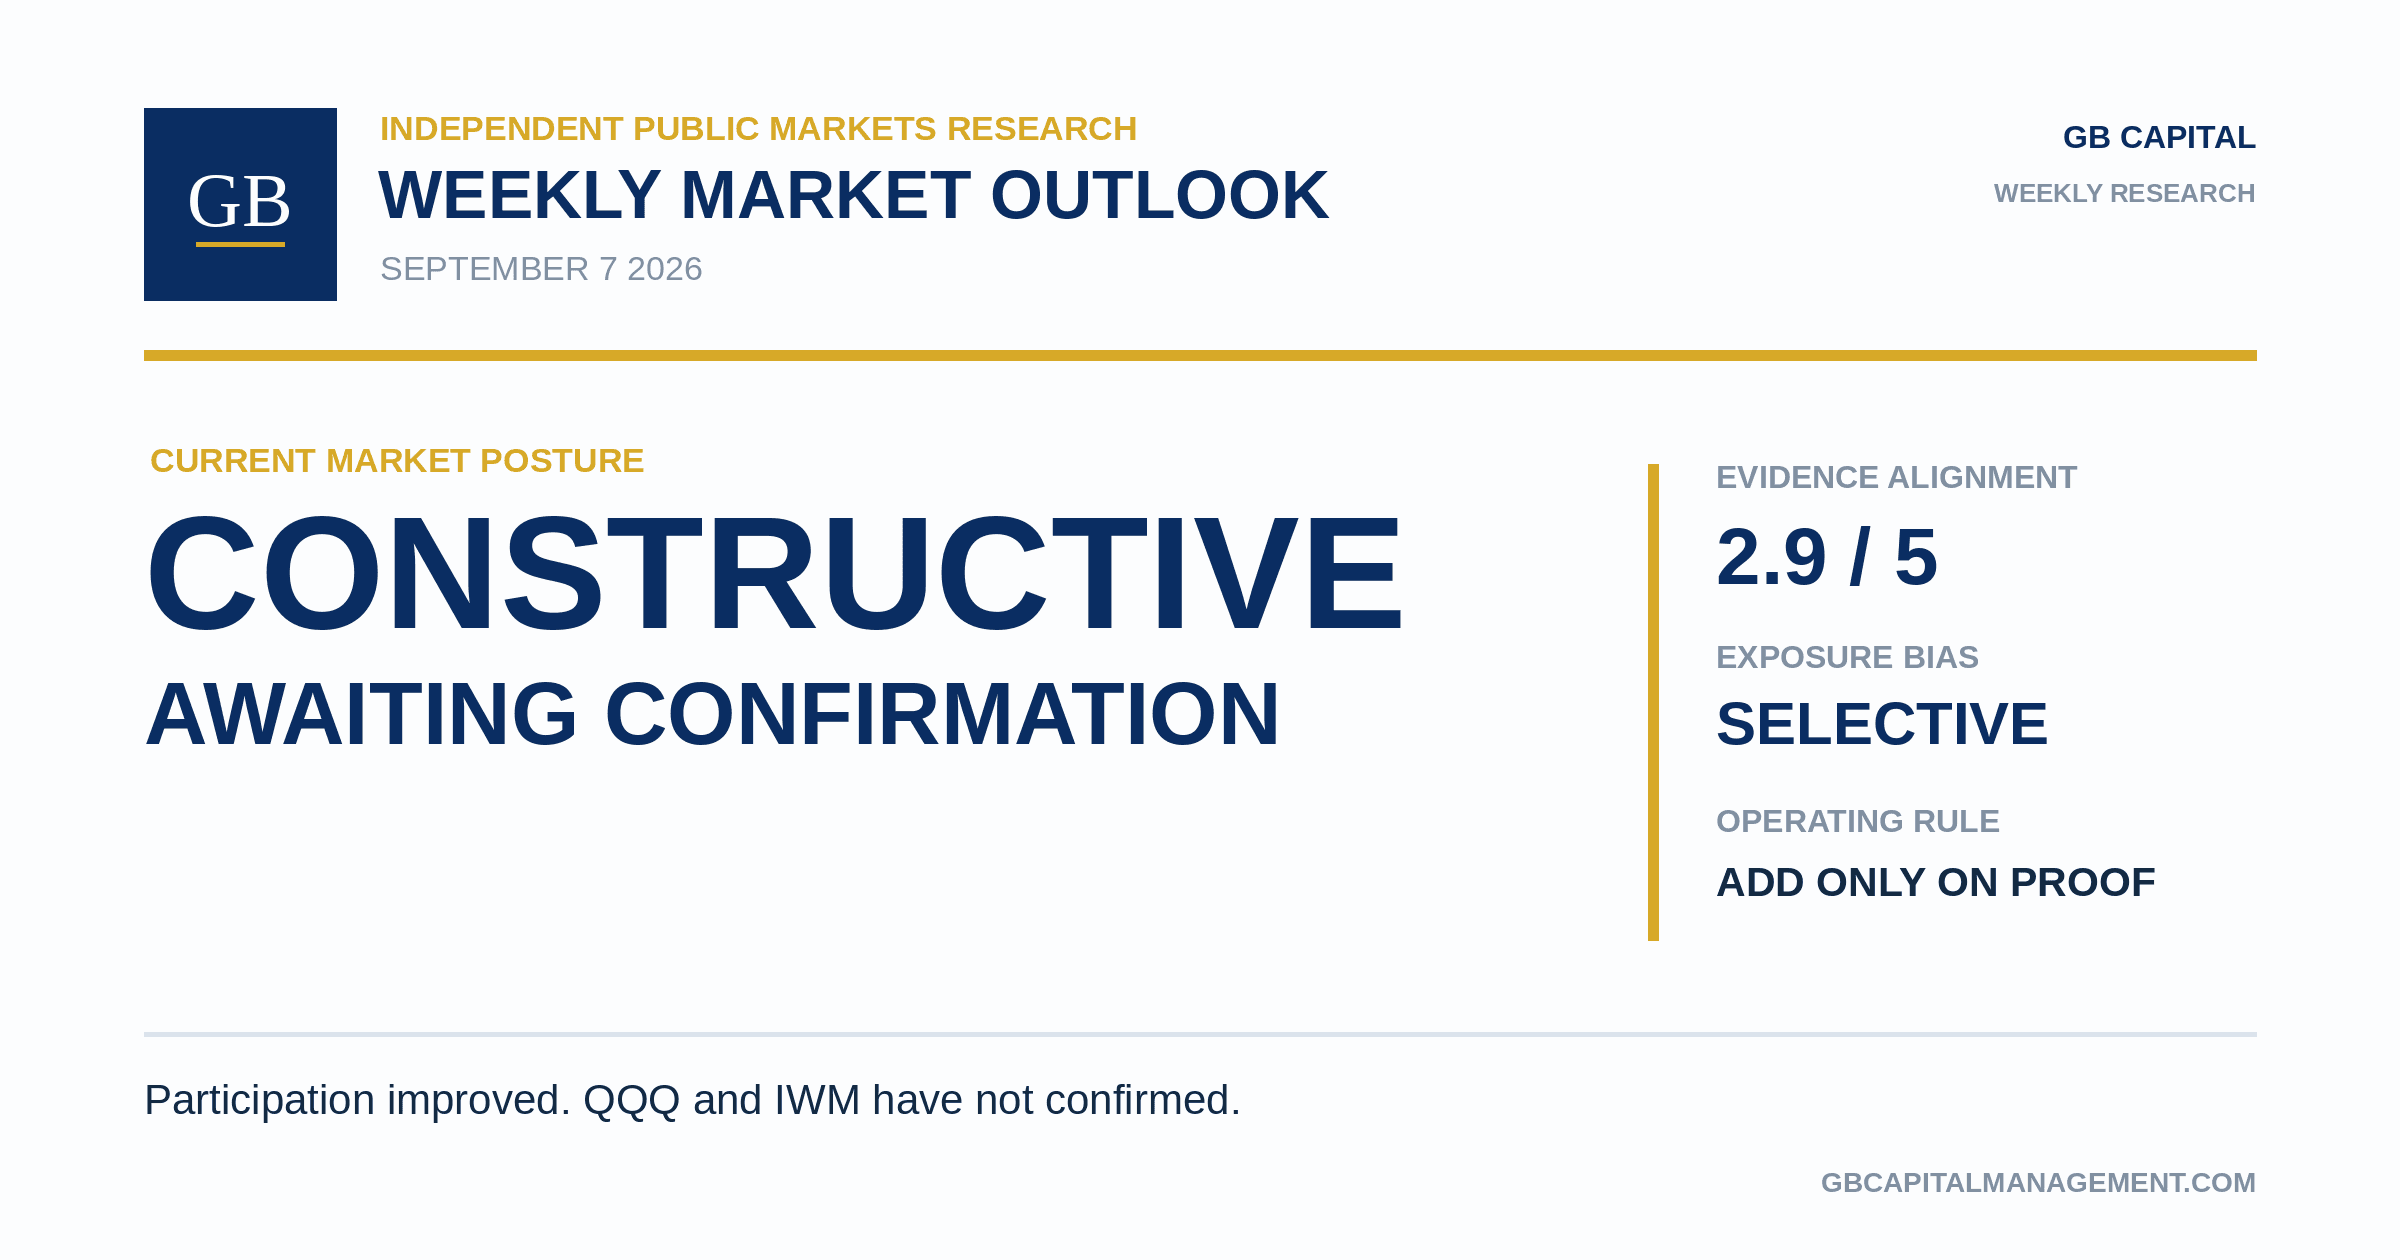
GB Capital Weekly Market Outlook · Week of September 7, 2026
Market posture: Constructive — cautious, wait and see
Evidence alignment: 2.9 / 5 — improving, just above neutral
Exposure bias: Selective — add only on proof
Current posture and operating translation
SPY and QQQ held their key levels while stage participation stabilized, prior leadership repaired and the setup list expanded. That earns a constructive posture, but it remains a wait-and-see one: QQQ is still inside its summer range, IWM has yet to confirm and several sectors continue to carry majority Stage 4 populations. The evidence supports selective exposure, not a broad increase in portfolio heat.
The 60-Second Read
The view moved from Cautious to Constructive because SPY and QQQ held their key levels while participation stabilized, leadership began rebuilding and the setup list expanded.
This is a wait-and-see posture rather than a bullish one. At 2.9 out of 5, evidence alignment sits just above neutral. QQQ is still rangebound, IWM has yet to confirm, and trend persistence and position feedback remain the missing proof.
What changed
Stage 2 stopped making new lows and began improving while Stage 4 stopped expanding.
Prior leaders in semiconductors, memory and AI infrastructure moved from repair toward early expansion.
The High Alert list expanded as more clean daily and weekly structures appeared.
Reasons for caution
QQQ remains inside the summer range, and IWM has yet to confirm broader risk appetite.
Technology, communication services and consumer discretionary remain majority Stage 4.
Trend persistence and position feedback are the two weakest dashboard readings at 2.25 and 2.5.
Rates near 4.78%, oil above $90 and this week's CPI keep event risk high.
Evidence Continuity
The Evidence Improved, but the Confirmation Tests Remain Open
The cautious posture last week described what was missing beneath resilient headline indexes rather than predicting a decline. Stage 2 participation was deteriorating, Stage 4 was expanding, prior leadership remained in repair mode, and the number of mature setups was too small to justify pressing.
This week matters because several areas that kept the framework cautious stopped worsening. The improvement is real and early. An evidence-based process should acknowledge the inflection while treating one week of better internals as something short of proof of a durable advance.
Evidence | Last week | This week | Decision impact |
|---|---|---|---|
Index structure | Rangebound, unresolved | Rangebound again, and early weakness was absorbed as QQQ finished above its 21-day EMA | Still unresolved; downside resilience is constructive |
Stage participation | Stage 2 shrinking; Stage 4 expanding | Stage 2 has started to improve; Stage 4 has stopped expanding | Internal deterioration is no longer accelerating |
Leadership | Thin and rotating | Prior semiconductor, memory and AI-infrastructure leaders are setting up again | Leadership quality is improving |
Setup proliferation | Limited | Many more mature daily and weekly bases are appearing | Clearest positive change, short of confirmation |
Trend persistence | Weak | Some structures are beginning to expand | Improved, and this remains the confirmation test |
Risk appetite | Selective | IWM strengthened Friday and is close to reclaiming the 21-day EMA | Better, and broad confirmation is still pending |
The burden of proof remains on follow-through
Internal repair is visible. QQQ still needs to resolve its range, IWM must confirm broader risk appetite and the best bases must become persistent trends. Until then, the posture stays constructive and selective.
GB Capital Decision Layer
GB Capital Market Evidence Dashboard
The composite is the equal-weight average of eight evidence states. It converts the full market read into exposure discipline rather than a forecast.
Evidence | Current read | Decision implication |
|---|---|---|
Primary trend | 3.5 / 5 — Constructive | SPY and QQQ remain above rising longer-term trend measures. The primary uptrend never broke. |
Index structure | 3.0 / 5 — Resilient, unresolved | QQQ remained rangebound, though early-week weakness failed to persist and price finished back above the 21-day EMA. |
Stage participation | 3.0 / 5 — Inflecting | Stage 2 has stopped making new lows and has started to improve while Stage 4 has stopped expanding. |
Leadership | 3.25 / 5 — Re-emerging | Prior leaders in memory, semiconductors and AI infrastructure are moving from repair into early expansion. |
Trend persistence | 2.25 / 5 — Early, unproven | The launchpads are present. The next step is proving that breakouts can hold and become intermediate trends. |
Risk appetite | 2.5 / 5 — Improving | IWM remains below its 21-day EMA while Friday strength brought it within roughly 0.3% of reclaiming that level. |
Setup proliferation | 3.25 / 5 — Expanding | The High Alert list is filling rapidly with mature daily and weekly structures, approaching full proliferation. |
Position feedback | 2.5 / 5 — Unconfirmed | Scale only as the best triggered setups hold risk, make progress and reward initial exposure. |
Operating bias
Maintain selective exposure in the best structures. Add only after breakouts hold and position feedback improves. The setup list is a leading clue rather than confirmation by itself.
Leadership Reset
Prior Leadership Is Repairing, but Not Yet Fully Restored
The clearest constructive evidence this week is that several areas that led earlier in the year are rebuilding the daily and weekly structures I look for before another intermediate move. That improves the opportunity set, but it stops short of proving that a new leadership cycle is underway.
Semiconductors and memory were two of the primary engines of the earlier advance, with MU and SNDK among the clearest leaders. After substantial corrections and weeks of repair, many of these names have recovered off their lows, built tighter bases and begun to expand again. They are potential launchpads rather than proof that the group has resumed leading.
DRAM: From Repair to a More Mature Structure
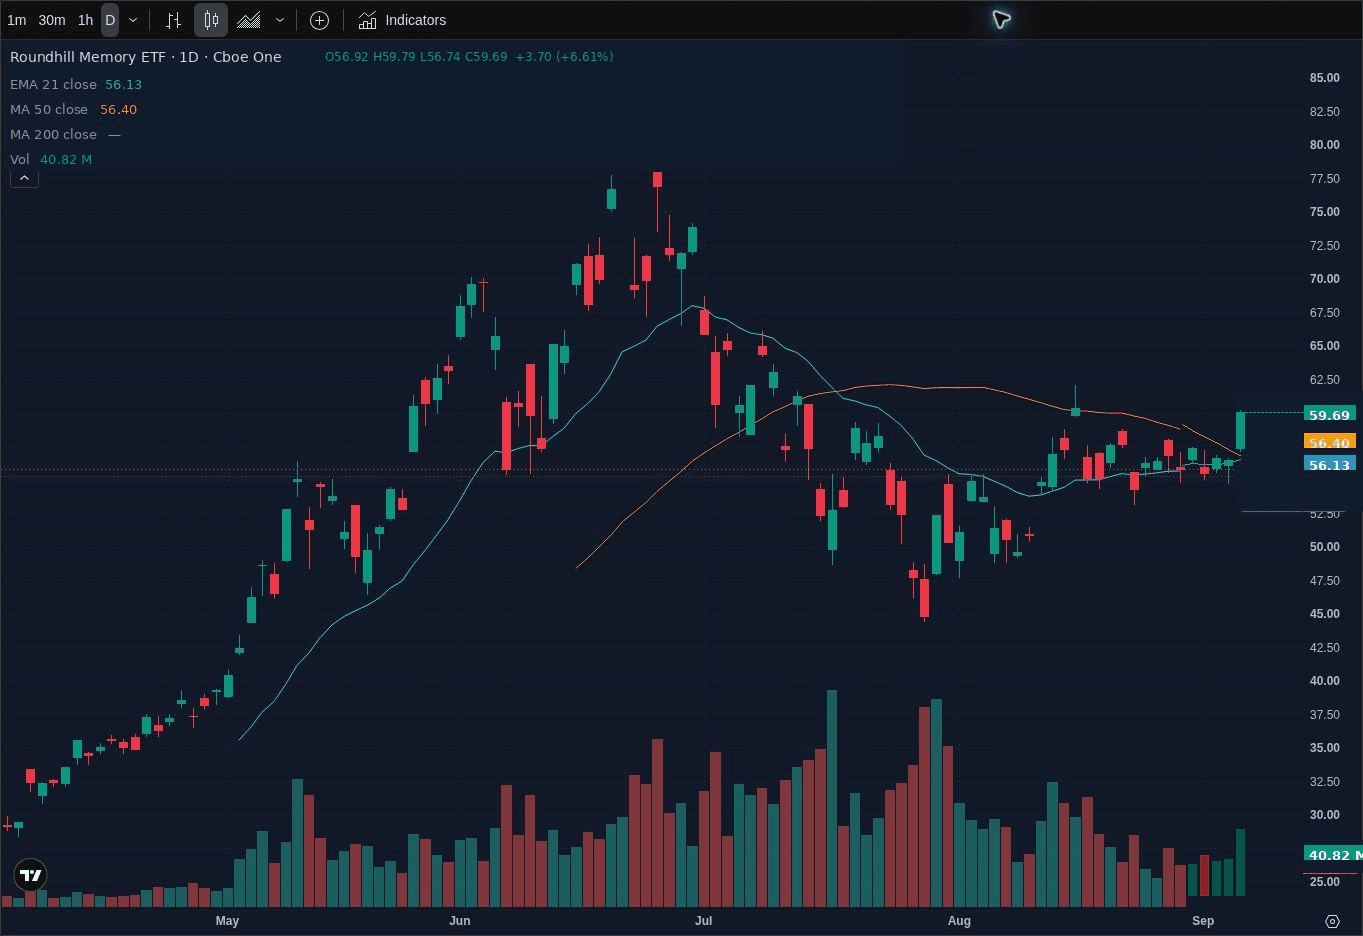
DRAM daily. Base chart TradingView through August 28, updated through September 4 using S&P Global Market Intelligence price data. Moving-average endpoints updated by GB Capital.
Last week: DRAM was still beneath its 50-day moving average and represented a group in repair.
This week: Friday changed that evidence. DRAM closed at 59.69 after a 6.6% advance, above an estimated 21-day EMA near 56.1 and 50-day SMA near 56.4.
What it means: That falls short of guaranteeing a new leadership run, but it is a meaningful step from repair toward early expansion.
Setup Proliferation
The Setup List Is Expanding Before Follow-Through Is Proven
For my process, setup proliferation is one of the most important leading indicators. When conditions improve, the watchlist begins filling with liquid leaders, mature daily and weekly consolidations, and entries close enough to support that risk can be defined clearly.
That is beginning to happen. There are more setups than there have been in a while, many in prior leaders rather than one-day momentum stocks. The gap between setup quantity and actual trend persistence is the single clearest reason the posture stays selective and patient.
Key distinction
The setup evidence has improved before the trend-persistence evidence has. The launchpads are appearing. I still need the launches to hold.
GB Capital Setup Monitor
Ticker | Area | Structural read |
|---|---|---|
SNDK | Memory / NAND | Prior-cycle leader; tight daily reset and constructive weekly base beginning to expand. |
MU | Memory / HBM | Prior-cycle leader; long correction has matured into a strong daily and weekly setup. |
SMTC | Semiconductors / connectivity | Weekly reset is firming and the daily structure is beginning to resolve higher. |
NBIS | AI infrastructure / cloud | Higher-beta AI name rebuilding above important weekly trend support. |
BE | AI infrastructure / power | Major prior advance followed by a deep reset; weekly structure is rebuilding constructively. |
LITE | Optical / fiber | Prior AI-infrastructure leader holding a constructive weekly base after correction. |
DELL | AI servers | Further along than most peers, showing that parts of the prior leadership complex can sustain expansion. |
HOOD | Fintech / higher beta | Long reset followed by a constructive weekly reclaim; useful risk-appetite evidence. |
Examples are included as market-structure evidence rather than recommendations. Structural reads are based on GB Capital daily and weekly chart review through September 4, 2026.
The common thread matters more than any individual ticker. Memory, semiconductors, networking, servers, data-center power and higher-beta growth are producing constructive structures at the same time. That is better than the isolated rotations that dominated the summer, and it becomes durable broadening only if the best structures trigger and hold.
What I need next
The High Alert list shows where opportunity is building. If the best bases trigger, hold and reward risk, exposure can rise.
Index Structure
QQQ Remains Rangebound Despite Resilient Support
QQQ spent another week inside the broad summer range. It started the week under pressure, traded back toward short-term support, and then recovered strongly enough to finish Friday at 718.96, above both its 21-day EMA and 50-day SMA while remaining well above the rising 200-day SMA.

QQQ remained rangebound last week, and early weakness was absorbed as the ETF finished back above key short-term trend measures.
Base chart TradingView through August 28, updated through September 4 using S&P Global Market Intelligence price data. Moving-average endpoints updated by GB Capital.
QQQ has repeatedly absorbed weakness while holding its primary trend. That resilience supports continued participation, but it leaves the range unsettled. The improving stock-level evidence matters because the longer-term trend is intact; clean range resolution is still required before the framework becomes more aggressive.
SPY and IWM Add Context
SPY followed a similar path: early weakness, then a recovery back above the 21-day EMA while the weekly trend remained intact. IWM is still the laggard, and Friday strength brought it to within roughly 0.3% of reclaiming its 21-day EMA. Small caps have yet to confirm broad risk-on behavior, while the warning is no longer worsening.
Participation and Structure
Stage Participation Has Stabilized, but Breadth Is Still Mixed
This is one of the most important changes from last week. Stage 2 stopped making new lows and began to improve while Stage 4 stopped expanding. The direction is better, and the sector table shows why the breadth signal remains incomplete.
Current Sector Stage Distribution
Sector | Stage 2 | Stage 4 | Interpretation |
|---|---|---|---|
Energy | 61% | 30% | Strong participation |
Financials | 58% | 23% | Strong participation |
Materials | 41% | 45% | Mixed |
Health Care | 39% | 44% | Mixed |
Information Technology | 28% | 46% | Repairing |
Industrials | 28% | 48% | Mixed |
Communication Services | 27% | 55% | Still weak |
Consumer Discretionary | 24% | 59% | Still weak |
Consumer Staples | 24% | 52% | Weak, mixed |
Utilities | 21% | 62% | Weak breadth |
Real Estate | 17% | 41% | Mixed, basing |
Source data: DeepVue stage analysis supplied September 7, 2026. GB Capital interpretation. Stage 2 = advancing; Stage 4 = declining.
The sector table also keeps the constructive case honest. Technology, communication services and consumer discretionary still carry large Stage 4 populations. This falls short of a fully healthy broad market. The improvement is an inflection rather than completion.
Stage participation signal
Stage 2 is beginning to turn higher while Stage 4 has stopped expanding. This is an early internal inflection rather than a fully healthy breadth signal.
Leadership Across Timeframes
Theme Data Shows Repair More Clearly Than Broad Leadership
The multi-timeframe theme data helps separate a short-term bounce from a broader leadership reset. Semiconductors are the clearest example: roughly flat over one and three months after a major earlier advance, positive over the latest week and still one of the strongest year-to-date groups. That is consistent with a group that corrected, repaired and is beginning to wake up again.
Theme | 1 week | 1 month | 3 months | YTD |
|---|---|---|---|---|
Semiconductors | +2.02% | -0.78% | -0.47% | +57.45% |
Artificial Intelligence | +1.98% | +3.83% | +2.88% | +26.46% |
Software | +2.13% | +5.18% | +9.10% | -1.06% |
Cybersecurity | +1.04% | -2.16% | +13.82% | +37.80% |
Oil and Gas | +5.59% | +9.04% | +3.09% | +50.13% |
Bitcoin | +1.73% | +23.95% | +32.48% | n/a |
Source data: DeepVue Theme Tracker through September 4, 2026. Theme definitions are DeepVue; selection and interpretation are GB Capital.
The market still contains substantial rotation. Semiconductors and AI-linked names are beginning to contribute again while software remains firm. That becomes meaningful broadening only if these related groups work at the same time and sustain their advances.
Leadership read
Re-emerging, but short of fully restored. The evidence is stronger because the setups are appearing in areas that already proved they could lead earlier in the cycle.
Macro as Context, Not Conclusion
Rates Remain a Headwind That Price Has Absorbed So Far
The macro backdrop remains difficult enough to deserve respect. August payrolls increased by 162,000 and unemployment held at 4.1%. The stronger labor report pushed Treasury yields higher, with the 10-year ending Friday near 4.78% and the 2-year near 4.37%. Oil also moved above $90 per barrel, keeping inflation pressure in focus ahead of this week's PPI and CPI reports.
Those facts are relevant because higher yields raise the burden of proof for long-duration growth assets. By themselves, they fall short of being the market call. The more useful question for my process is how equities are responding to that pressure.
Market response
Major indexes continue to defend support and more bases are maturing despite elevated yields, higher oil, inflation uncertainty and difficult September seasonality. That response is constructive so far, and the burden of proof remains higher for long-duration growth assets.
Key Events This Week
When | Event | What I am watching |
|---|---|---|
Thursday 8:30 AM ET | August PPI and weekly jobless claims | Whether yields jump and whether emerging growth leadership absorbs the response. |
Friday 8:30 AM ET | August CPI | The week's main inflation test. Price response matters more than predicting the print. |
Friday 10:00 AM ET | Preliminary September consumer sentiment | Secondary read on confidence and inflation expectations. |
Inflation schedule: U.S. Bureau of Labor Statistics. Weekly claims: U.S. Department of Labor. Consumer sentiment: University of Michigan Surveys of Consumers.
September seasonality remains a secondary overlay rather than a standalone bearish thesis. The market knows the calendar. If price continues to hold support and the opportunity set continues to improve through a historically difficult month, that behavior deserves more weight than the seasonality statistic itself.
Decision Rules
The Constructive Case Still Needs Confirmation
The current view is constructive and conditional. Internal evidence has improved enough to support selective participation, but not enough to assume the indexes resolve higher. Greater confidence requires persistent Stage 2 improvement, broader risk appetite and successful follow-through from the developing bases. Renewed deterioration, failed bases or sustained index weakness would move the posture back toward cautious.
Evidence That Strengthens the View
QQQ and SPY resolve their ranges higher and hold the move.
Stage 2 continues rising while Stage 4 remains capped or begins to contract.
IWM reclaims its 21-day EMA and broader risk appetite improves.
Memory, semiconductor and AI-infrastructure bases trigger and hold.
The High Alert list becomes true setup proliferation and actual positions reward risk.
Evidence That Weakens the View
QQQ and SPY lose short-term and intermediate support and fail to reclaim it.
Stage 2 resumes making new lows while Stage 4 starts expanding again.
IWM rolls back over and broader risk appetite weakens.
Former leaders resolve their maturing bases lower rather than higher.
The setup list contracts and early positions repeatedly fail.
Current Action Plan
Portfolio heat: Keep exposure selective. Increase only as the best structures trigger, hold and receive positive position feedback; the evidence has yet to earn maximum heat.
New positions: Favor mature daily and weekly bases in improving leadership groups, especially where risk can be defined close to support.
Adds: Require price progress. The strongest setups should hold, attract demand and make measurable progress before size increases.
Correlation: Keep multiple AI-related setups from quietly becoming one oversized factor bet.
Cash: Cash remains valid optionality while range resolution, broader risk appetite and trend persistence remain open.
Before Any New Risk
Leadership: Persistent relative strength and evidence that the group can lead rather than simply bounce.
Theme and evidence: At least three of four — technicals, fundamentals, catalyst and narrative.
Structure and timing: A mature base, volatility contraction and an entry near enough to support that risk is clear.
Risk and confirmation: Clear invalidation, asymmetric reward and price beginning to prove the thesis.
Bottom Line
What I Think Matters Most Right Now
Last week: I said the market was healthy enough to hold and short of the condition required to press, because the indexes were masking deteriorating participation and a shortage of mature setups. The primary trend was intact, but the market had yet to earn greater aggression.
This week: The evidence changed. QQQ and SPY once again absorbed early weakness. Stage 2 participation stopped making new lows and started to improve while Stage 4 stopped expanding. The High Alert list expanded. Long bases in memory, semiconductors and AI infrastructure matured. MU, SNDK and a growing list of prior leaders moved from repair toward early expansion.
That is the evidence I care about because it comes directly from what the market is doing. Rates are elevated, oil is higher, inflation data are coming and September seasonality is difficult. Those headwinds could matter. So far, the market is absorbing them while the opportunity set improves.
Bottom line
My tactical posture is constructive and cautious, which in practice means wait and see. SPY and QQQ holding their levels is the constructive anchor, and the evidence supports selective participation as mature setups trigger while actual breakout and position feedback determine whether exposure expands. QQQ and IWM still owe the framework confirmation, and sustained index weakness would move the view back toward cautious.
Sources and Disclosures
Framework and interpretation: GB Capital Management LLC. Stage and theme data: DeepVue, supplied September 7, 2026. QQQ and DRAM base charts: TradingView through August 28, updated through September 4 with price data from S&P Global Market Intelligence via StockAnalysis; moving-average endpoints cross-checked against public technical data. Inflation release schedule: U.S. Bureau of Labor Statistics. Weekly claims: U.S. Department of Labor. Consumer sentiment: University of Michigan Surveys of Consumers.
Disclosure: This material is provided for informational and educational purposes only and should be construed as general market commentary rather than investment advice or a recommendation to buy or sell any security. Individual securities are shown only as examples of the market evidence discussed.